

For most of history, if you wanted another exceptional mind, you had to wait for another person. You could build a school, fund a laboratory, attract immigrants or hire someone away from a rival. You could give a talented person better tools. You could not make a thousand copies of them before breakfast.
Much of civilisation was organised around that limitation: who received an education, who could afford expertise, which problems deserved the attention of the few people capable of solving them. An extraordinary amount of human ambition died waiting for someone with the time and ability to pursue it. We are beginning to change that. Something we once had to raise can increasingly be manufactured. What happens to an economy built around its scarcity?
My starting conviction is that intelligence will become abundant faster than the world can reorganise around it. That gap can create fortunes. It can also ruin investors who mistake a temporary shortage for a permanent right to charge. When Intelligence Is Free is my investment research into how this transition unfolds, which parts of the emerging economy are worth owning, and how to invest in them through public markets.
The most expensive thing we learned to copy
We have been copying the products of intelligence for centuries. A book lets a million readers benefit from one person’s discoveries. Software repeats a procedure as often as we need it. But when the next problem required fresh judgment, we usually had to return to a person. Knowledge could travel much further than the mind that produced it; the supply of people able to put it to work remained a constraint.
AI begins to separate useful cognitive capability from the person supplying it. Developing a model can cost a fortune, but serving its next customer does not require another childhood, education and career. It requires computing resources. Better chips and more efficient models reduce the resources needed for a given result. The frontier can become more expensive to create while yesterday’s frontier becomes cheaper to use.
The decline is already measurable. In The plunging price of thought, published on 22 September 2026, Epoch AI estimated that the cost of reaching a given performance level had fallen about 47% per quarter since 2023, roughly thirteenfold per year. These are benchmark results, not the full cost of dependable work inside a business. But the speed at which expensive capabilities become inexpensive inputs is extraordinary.
Competition brings that improvement to the buyer. In May 2026, Epoch estimated that leading downloadable models trailed frontier closed models by about four months on its aggregate benchmark measure. A customer does not need the best model ever created for every assignment. Once several systems can do the job, yesterday’s miracle becomes something buyers can shop around for. Epoch’s cost curve assumes buyers keep choosing the cheapest suitable model, while real users switch less often: cheaper intelligence can arrive long before the saving reaches their software bill.
My working assumption is that over the next decade AI will do essentially all the work we now do at a computer better and far more cheaply: writing software, analysing accounts, designing products and running everyday operations. As that intelligence moves into robots, much physical work should become cheaper too. “Almost free” describes a world where skilled work can be bought for a fraction of today’s cost. That changes what people can afford to attempt, and what businesses can charge to do it for them.
Which part of the invoice survives?
A company adopts AI, lowers its costs and expects to keep the saving. Then its customer acquires the same capability. So does its competitor. What looked like a margin improvement inside one business becomes a renegotiation across an industry. The work still matters. The old price no longer commands the same authority.
There is an intellectual inheritance here. Joel Spolsky explained why firms benefit when their complements become cheap. Christensen and Raynor described how profit opportunities migrate as parts of a value chain become commodities. Those ideas tell us where to look. But profits lost by one business do not have to become profits for another. I expect a substantial share of the gains to reach customers as lower prices, or make previously unpaid activities possible, without becoming durable corporate profit anywhere. The research question is which part of the invoice survives, and which new activity can earn one.
Substitute starts with the threatened invoice. On 3 February 2026, RELX shares fell about 14% during a selloff following Anthropic’s new legal tools. By July, RELX was reporting 10% underlying revenue growth in its Legal division for the first half, with adoption of its own AI-enabled platform supporting growth. The market feared that generating legal answers would destroy the business. Customers were still paying for a product combining AI with verified legal content and an established workflow. Those results do not settle the long-term threat. They show why replacing a task and replacing the business that makes its result usable are different propositions.
The opportunity can belong to a new provider taking over the function, or to an incumbent whose valuable position survives the destruction of its old product. RELX is a case to investigate, not proof that every information business is protected. If the customer can obtain the content, reliability and workflow elsewhere, the remaining invoice comes under pressure too.
Amplify begins when the customer uses cheaper intelligence to do more. Occasional analysis becomes continuous analysis; software agents carry out more transactions; robots enter work that could never justify a robot before. All that activity needs power, cooling, equipment, connectivity and ways to establish identity and permission. In the quarter ended August 2026, Oracle reported 121% growth in cloud-infrastructure revenue and $664 billion of remaining performance obligations. The first measures revenue already earned; the second is contracted revenue still to be recognised. Both explain why so much capital is chasing the physical means of supplying intelligence. Neither tells us what return the last unit of new capacity will earn.
Reprice concerns things cheap intelligence cannot copy. You may be able to summon a castle in virtual reality. You cannot summon another stretch of Mediterranean coastline. If AI makes people richer, more money can chase the places and experiences they still want in the physical world. Yet the virtual castle could also change what they want to pay for. And if work no longer forces them to live in an expensive city, they may leave. Some places will discover that their scarcity was partly captivity. Monetary assets involve another mechanism: how governments finance the transition and how much confidence survives in the money used to hold wealth. I explore that mechanism in the section on the sovereign balance sheet in Every Technology Boom Borrows From the Future.
Unlock goes beyond redistributing existing spending. Some demand never appears in today’s accounts because serving it has always cost too much. A useful service requires more expert attention than its customers can afford. A neglected problem never gets a team. Cheap intelligence changes which problems can receive sustained attention.
Consider a rare disease whose genetic cause remains unexplained. In a case described by Google DeepMind, researchers at the Broad Institute used AlphaGenome Atlas to prioritise a variant in the DNM1 gene. Its prediction of a faulty splice site supplied supporting evidence that helped resolve the case. The model had given researchers a promising place to look in an enormous field of possibilities. A prediction still needs investigation, and a diagnosis still needs a treatment. But making that search affordable can bring previously neglected problems within reach. The investment question is who can turn the new capability into a service people can use and pay for. DeepMind offers Atlas free for academic research and has announced commercial access through Google Cloud, so the business collecting the new fee may be the model owner itself.
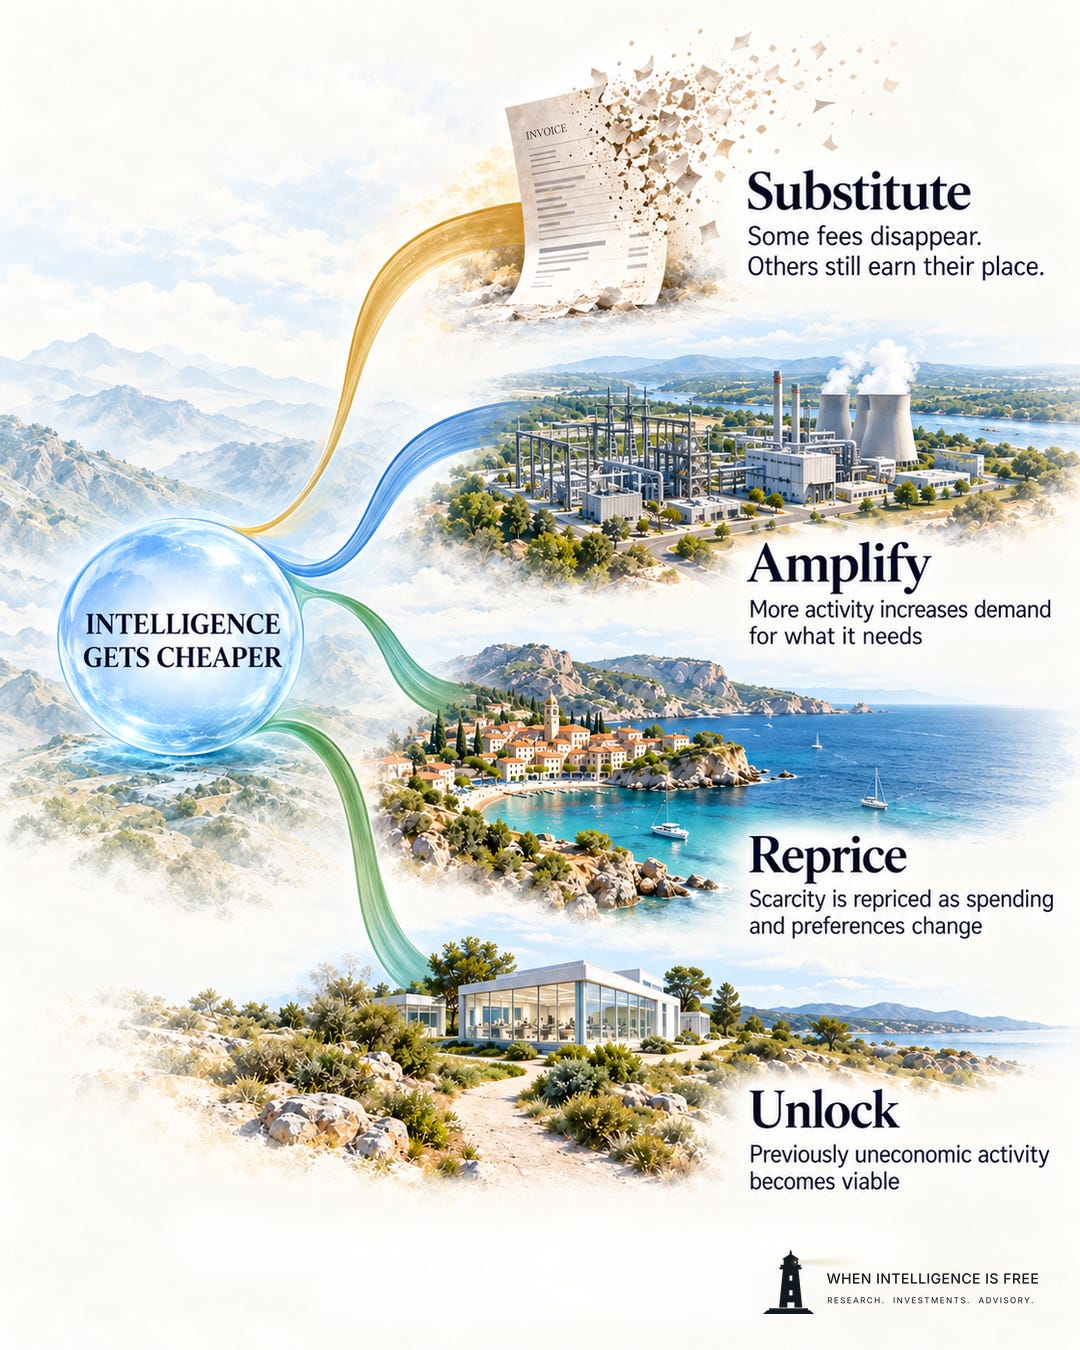
These four movements happen together. The service replacing an old fee consumes infrastructure, releases spending and makes another activity possible. They take the opportunity far beyond the companies selling models. They also bring us to the next difficulty: identifying what could become valuable is much easier than knowing when it will become a business that pays.
A condition in the plan is not a condition delivered
Across my career in transformation consulting, only one project ran to plan: a bank launching an insurance company from scratch. It was a greenfield business, with no dependencies on existing systems, one owner rather than a collection of shareholders, and that owner deeply involved in the project.
In every other case, delays ranged from six months to three years. Their scale depended on how many of the client’s commitments and preconditions failed to materialise. These were assumptions we had discussed at the start, not obstacles nobody had thought to mention. The exceptional project worked because the conditions behind its timetable could actually be delivered.
That experience shapes where I look for the first beneficiaries. A new business with an involved founder can build around the capability from the beginning. An established company has to change systems, incentives and decisions that already belong to somebody. The bank’s new insurer shows that an incumbent can create the same freedom, but has to give it real authority. My inference is that the ability to act without renegotiating the whole organisation may matter more than the size of the AI budget. It gives Unlock a head start and makes the defence described in Substitute a transformation project of its own.
Now lend money to the infrastructure waiting for those transformations. The model can improve on schedule while the organisation that intends to use it is still trying to make its own plan true. Interest, meanwhile, arrives according to the contract.
Shareholders finance the wait too. In the quarter ended August 2026, Oracle sold $20 billion of new shares through its at-the-market programme. The buildout gained cash; each existing share represented a smaller fraction of the company.
Customers have made promises of their own. The latest filings from Microsoft, Alphabet, Amazon and Oracle, covering June and August 2026, together disclosed more than $2.3 trillion of remaining contracted revenue. That total spans software and cloud services, includes amounts already billed, and cannot be treated as AI debt. It shows how much future business has already been promised.
Some of those customers have committed to paying for capacity whether they use it or not. CoreWeave’s filings describe take-or-pay contracts that begin on a fixed date or when the specified capacity is delivered. Its large customers include AI labs and cloud providers. Part of the revenue they need to earn from this capacity must come from thousands of organisations like those I helped transform. A strong balance sheet can fund the wait, but cannot make those organisations adopt faster. For delivery-triggered contracts, the bill runs on the infrastructure timetable. The earnings needed to cover it run on the adoption timetable. In all but one of my transformations, that second timetable slipped by six months to three years. A contract can make the customer pay for an idle machine. It cannot make the machine profitable for the customer.
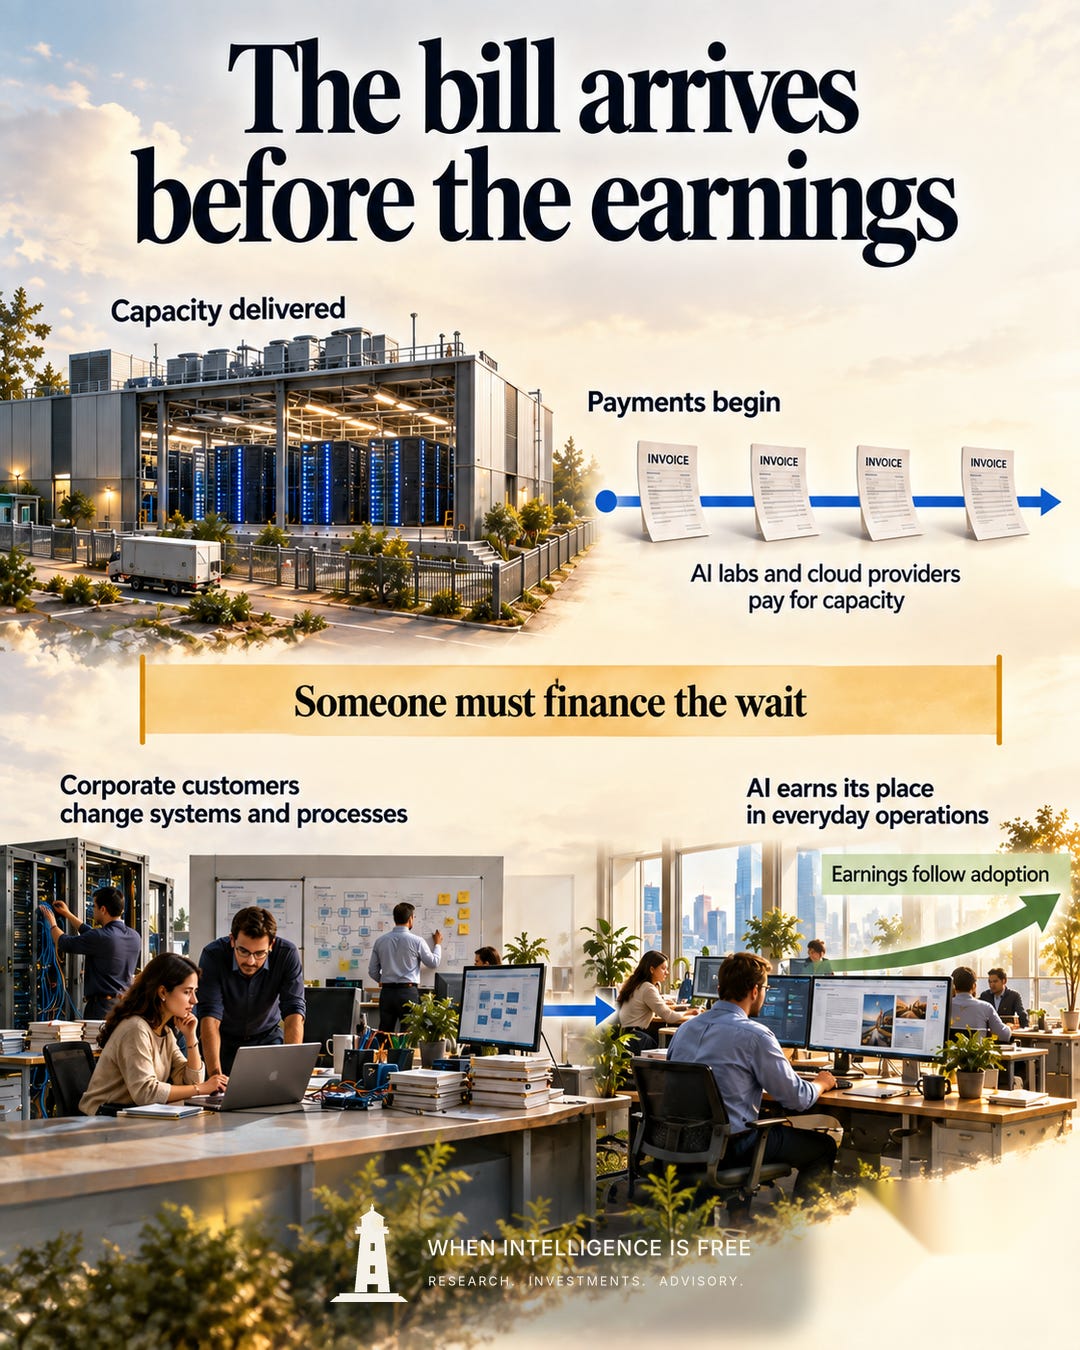
This is the AI capital cycle: Buildout → Digestion → Diffusion. During Buildout, expectations about tomorrow’s demand finance today’s capacity. Suppliers can earn before their customers have discovered how to earn from the equipment. The orders are real. What remains uncertain is whether the eventual revenue will reward all the capital committed along the way.
Digestion begins when those promises meet operating results. Adoption takes longer, new capacity weakens prices, or a better model changes the economics. Investment slows, contracts change and assets are repriced. In a gentle adjustment, demand grows into the capacity. In a harsher one, creditors become owners and the person who financed the future is removed from it. The technology need not fail for its original financing to fail.
Diffusion is the wider economy reorganising around capability that is dependable and affordable. A later business can rent capacity cheaply, acquire an asset after a restructuring or begin with a better generation of equipment. It benefits from work already done without paying the original bill. Its attractive economics may depend on somebody else’s disappointing return. These phases overlap: a component can remain scarce while its buyer’s finances deteriorate, and useful services can spread while another part of the industry digests excess capacity.
That is why being right about what the world will need is insufficient. The original shareholders may not survive to own it, or today’s price may already demand too much of tomorrow. I develop this conflict in Every Technology Boom Borrows From the Future. Here it supplies the time dimension of the investment: what becomes necessary, when it starts paying, and who still owns it by then.
When the map stops working
The argument so far describes the world I consider most plausible: Powered Diffusion, where intelligence keeps improving and spreading while the rest of the economy adapts unevenly. The four movements identify where to investigate; the capital cycle explains why the opportunity changes along the way. But an investor can understand both and still be wrong about the world they are entering.
In Plateau, models remain useful assistants but fail to become reliable autonomous workers. The demand financed into today’s capacity never fully arrives. In Discontinuity, a handful of laboratories achieve such a large advantage that they absorb the businesses investors expected to prosper around them. The supplier becomes its customer’s competitor, and the biggest winners may remain private. Knowing who won would not guarantee that an ordinary investor could buy a meaningful share of the victory.
Abundance Shock attacks the thesis through success. Better algorithms reduce computing needs, energy supply expands and robotics makes physical production much easier to scale. The world catches up with its new intelligence faster than expected. The machines have helped build their way out of the scarcity you bought. New constraints may emerge without lasting long enough, or remaining accessible enough, to reward public shareholders.
Politics can change the result even if the technology develops exactly as expected. A government losing payroll revenue must find another way to fund services and sustain household purchasing power. It can broaden ownership, tax profits to purchase provision, or make essential systems public utilities with capped returns. A humane, orderly settlement may leave citizens richer in things they can use and investors poorer in profits they can collect. The claim to the output matters as much as the output itself. That is the question I explore in Who Owns the Machines That Replace You?
The framework assumes systems remain sufficiently aligned with human purposes and under human control, governments hold together, contracts and property rights retain meaning, and some businesses earn profits their shareholders can receive. Redistribution and regulation fit inside those assumptions; the disappearance of investable private profits does not. A cleverer stock list cannot repair every possible future.
Owning the transition
When Intelligence Is Free turns this argument into research on public transition beneficiaries and a public investment book with positions, returns and reasoning. A business must matter in the economy emerging around it, retain a worthwhile share of what it creates, and be available at a price that leaves something for its owner. A company can satisfy the first condition and fail the other two.
RELX shows how I apply those three conditions. Reliable legal work remains necessary; the next question is whether customers still need RELX to obtain it. The Legal division’s growth gives me evidence of value retained, but I look for renewals and pricing that survive competing AI products. Then I ask what the share price requires me to believe. I value the cash the business could produce if legal answers keep getting cheaper, and compare that with the price of the whole group. A share-price fall creates an opportunity only if the business has lost less value than the market assumes. RELX is in my public investment book at publication; the book and its reviews are where I explain and update the case for owning it.
My monthly and quarterly reviews show how new evidence changes the investment case and the book. If competitors keep passing each productivity gain to customers, I stop treating that gain as something shareholders own. If capacity keeps arriving while customers postpone deployment, I put more weight on who can finance the wait. If supply expands faster than demand and pricing power disappears, I stop valuing yesterday’s shortage as a permanent asset. These are reasons to change an investment, even while the technology keeps getting better.
I expect the uneven world to offer factories to build, organisations to change, services to invent and problems worth solving. Some will make excellent investments. Others will improve life while disappointing their owners. An investor cannot make every holding a wish for some human problem to remain unsolved.
For most of history, ambition had to wait for enough capable people. We are beginning to remove that limit. The next constraint may be power, the means to act on an idea, permission to proceed or a claim on what the machines produce. Each has different owners and a different life expectancy. The task is to recognise when something useful becomes worth owning, and when the world has learned to do without the scarcity we bought.
When intelligence is free, I want to own what the world is trying to do next.
When Intelligence Is Free is independent research on where economic value moves as intelligence becomes abundant. Explore the framework, see how the thesis is expressed in the public investment book, or apply the same reasoning to a company or market decision through advisory.